Tactic bridging complementary route lengths comes amid rival's mega-merger, rebranding
Airlines make for tricky bets in private equity, where fuel swings, currency moves and lease bills mean that more passengers don't always add up to bigger profits. Yet for VIG Partners, a Seoul-based buyout fund that already owns budget carrier Eastar Jet, it seems one airline isn't enough.
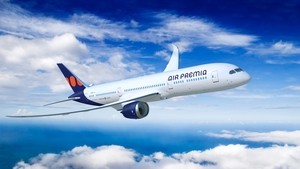
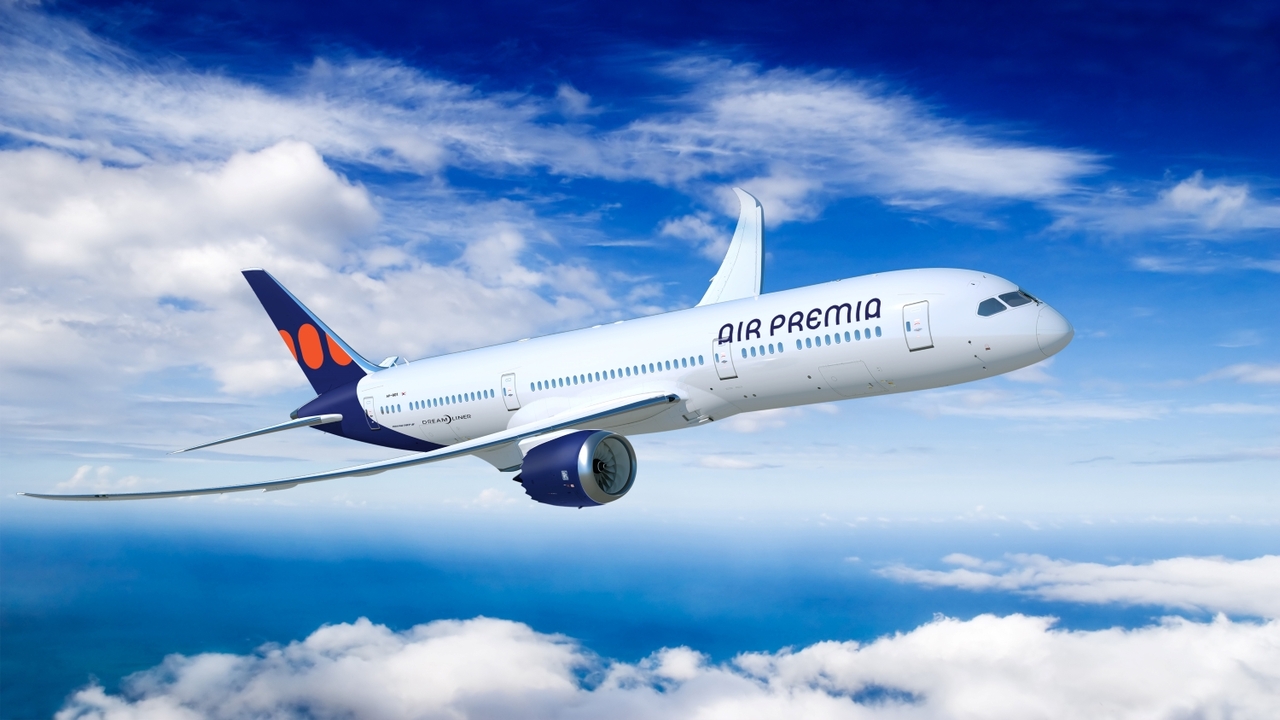
Industry sources said Tuesday that VIG was weighing a bid for Air Premia, a long-haul hybrid carrier that undercuts full-service airlines on fares while still offering perks like roomier seats and in-flight meals.
VIG has hired Bain & Company and begun due diligence on the roughly 70 percent stake split between AP Holdings, which holds 48 percent, and Tire Bank, which holds 22 percent. Sources said the price under discussion is near 300 billion won ($222 million).
Synergy in consolidation
The fund appears intent on pairing Air Premia's long-haul network with Eastar's short-haul routes, building a broader portfolio it can eventually sell as one package.
Eastar's fleet of 737s serves short-haul routes across Japan, Southeast Asia and Taiwan, while Air Premia's 787-789s fly long-haul routes to Los Angeles, New York, San Francisco and Washington.
"The routes barely overlap, so they complement each other," one industry official said.
Should the deal go through, VIG is expected to run the two as separate legal entities under one owner, a structure that preserves both brands but limits the cost savings that come from shared crews, maintenance and ground handling.
"The two airlines have different core routes and business models, so rather than merging, VIG is likely to run them independently and improve their scale and financial structure," the official added.
VIG bought Eastar Jet in 2023 and has since poured roughly 210 billion won into its recovery. Last year the fund began sounding out buyers at a valuation of 500 billion to 600 billion won, though Eastar alone no longer seems enough for a clean exit.
Some officials warned that rivals could outgrow Eastar's turnaround, worsening VIG's exit conditions, with the Air Premia pursuit partly protecting that asset's value.
Others pointed to VIG's pandemic-era turnaround of Eastar Jet as a model, suggesting the fund could run both carriers independently before a joint sale once finances strengthen.
Eastar Jet posted record revenue of 630.1 billion won last year, up 36.6 percent from a year earlier, narrowing its operating loss to 20.7 billion won from 28.7 billion won. Air Premia crossed 500 billion won in annual revenue for the first time, reaching 593.6 billion won, but swung to a 32.1 billion won operating loss.
Behind the urgency sits a rival consolidation.
Jin Air, Air Busan and Air Seoul, the three budget carriers under Hanjin Group, are set to merge into a single airline under the Jin Air name in March, combining a fleet of 58 aircraft into the country's largest low-cost carrier.
Against that backdrop, VIG's approach reads as an attempt to secure a defensible niche. Eastar's fleet consists of 24 planes as of September, and Air Premia has nine jets, putting the combined pair at 33, still far short of what a unified Jin Air will field.
Trinity Airways' own transition adds another layer to the competition. Under its rebrand, the carrier is moving away from a pure low-cost model toward what it calls a "selective service carrier," keeping short-haul fares low while adding upgraded lounges, entertainment and meals on medium- and long-haul flights.
"As mergers and acquisitions drive consolidation among low-cost carriers, securing scale is becoming more important," another industry official said. It will be just as critical to run the fleet efficiently and find new, less competitive routes to stay ahead, they added.
minmin@heraldcorp.com